08 8182 5555

SMSF property finance needs the right structure before the contract

Borrowing through a self-managed super fund is highly regulated. Loan, trust and contract details need to align before the purchase proceeds.

  • Residential and eligible commercial property finance
  • Limited recourse borrowing arrangements
  • Bare trust and contract-timing considerations
  • Specialist lender comparison
08 8182 5555
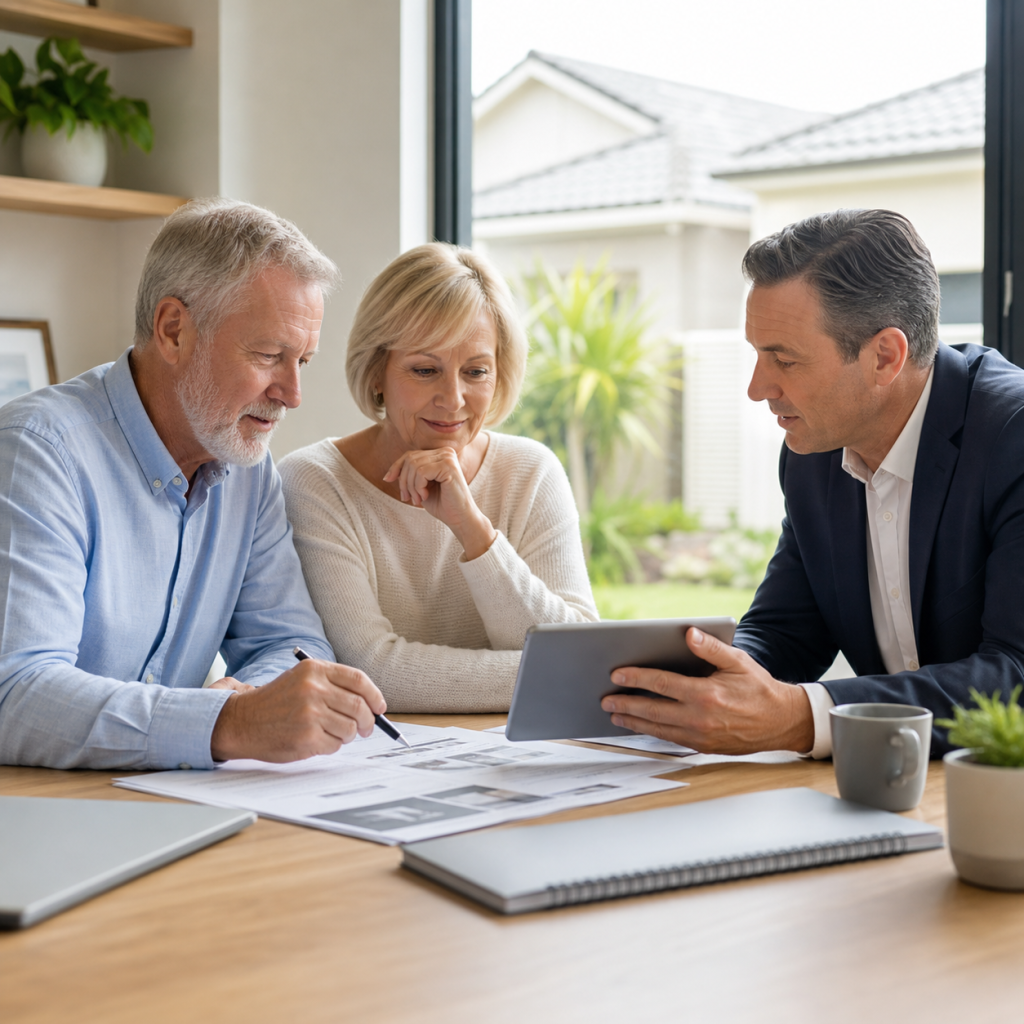
Australian couple reviewing SMSF property finance with a broker
SMSFStructure
PropertyLending
AdviceFirst
South Australian Owned Independent and local
Established in 1999 Decades of experience
Licensed credit provider Australian Credit License 385791
Bank + non-bank options Approved lender panel
SMSF property loan discussion in a bright Australian home office

SMSF property loans in Adelaide

SMSFs are generally prohibited from borrowing except in limited circumstances, including a correctly structured limited recourse borrowing arrangement. The loan is only one part of the process.

Before signing a contract, obtain advice from an SMSF-experienced financial adviser, accountant and solicitor. AAA provides credit assistance, not legal, tax or financial product advice.

If a property is not being purchased through a self managed super fund, standard investment loans may be the more relevant starting point. Where the SMSF is considering commercial property, commercial finance information can help explain how the property type and lease may affect assessment.

How a mortgage broker helps with an SMSF property loan

  1. Start with your strategy and advice

    We clarify your finance requirements and explain when specialist legal, tax and financial advice is needed before you sign a contract.

  2. Check your proposed structure

    We review your borrowing entity and holding trust documents against lender requirements alongside your professional advisers.

  3. Assess your SMSF’s lending position

    We review your fund’s contributions, liquidity, expected rent, servicing position and proposed property.

  4. Compare SMSF lenders

    We compare suitable deposit, rate, fee, liquidity and limited recourse lending requirements.

  5. Manage your finance approval

    We lodge your application and coordinate the valuation, lender conditions and settlement requirements with your advisers.

SMSF property loan FAQs

It may borrow under a permitted limited recourse borrowing arrangement that meets superannuation law and lender requirements. Incorrect structuring can have serious consequences.