08 8182 5555

Bridge the gap between your current home and the next

Bridging finance may help you buy before selling, but the timing, valuation and sale assumptions need to be realistic.

  • Calculate peak debt and expected end debt
  • Understand the bridging period and repayments
  • Plan the sale price and time buffer conservatively
  • Compare bridging with selling first or renting temporarily
08 8182 5555
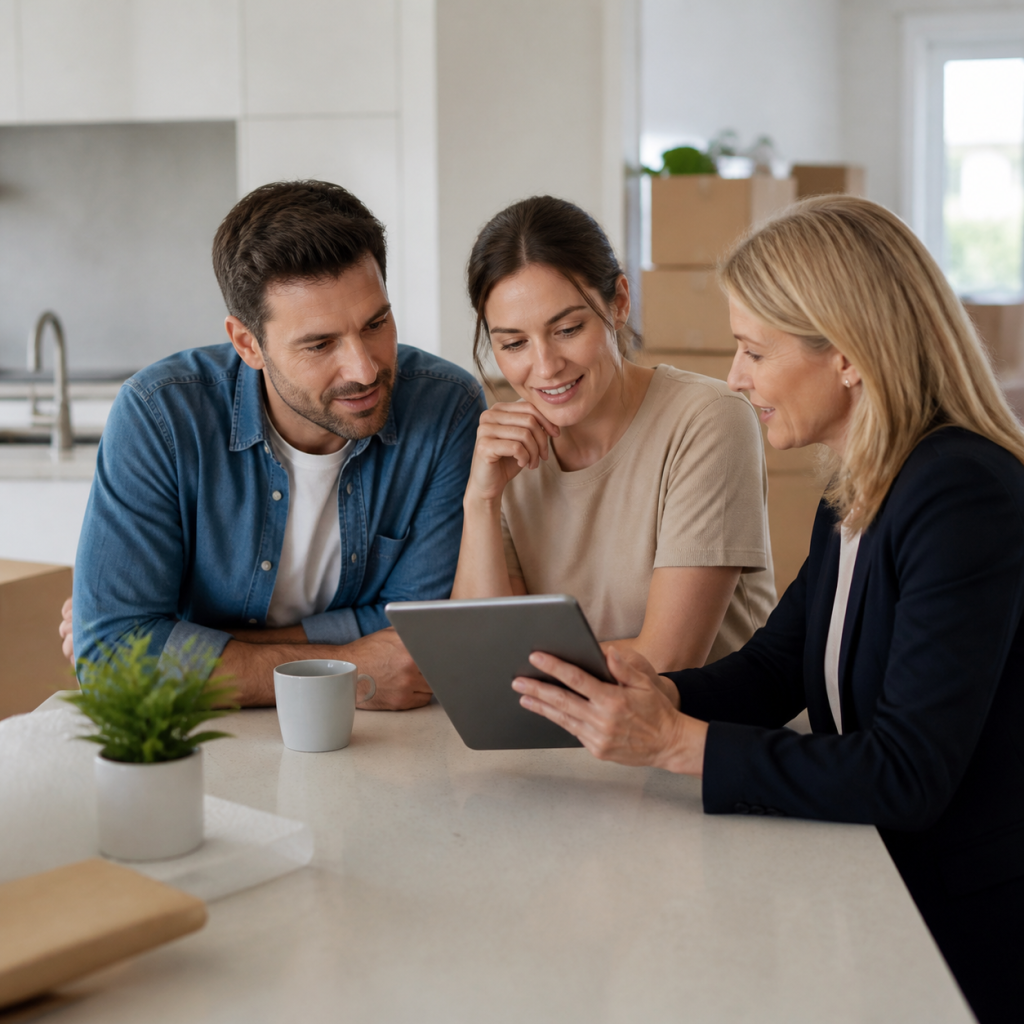
Australian couple reviewing bridging finance while moving house
BridgeFinance
PeakDebt
SaleTiming
South Australian Owned Independent and local
Established in 1999 Decades of experience
Licensed credit provider Australian Credit License 385791
Bank + non-bank options Approved lender panel
Broker explaining bridging loan timing to Australian homeowners

What is a bridging loan?

A bridging loan is short-term finance used when a new home settles before the current home is sold. The lender assesses the peak debt while both properties are held and the end debt expected after sale proceeds reduce the loan.

Bridging is useful only when the borrower can meet the lender’s requirements and has a credible sale and fallback plan.

Bridging finance is commonly considered during next home buyer planning because the lender assesses the existing property, new property and expected sale proceeds together. Home loan pre approval may help clarify the likely position before a purchase, while a refinance review may be relevant if equity needs to be reorganised first.

How a mortgage broker helps with a bridging loan

  1. Review your properties and timing

    We estimate your current home’s value and selling costs and review the price and costs of your new purchase.

  2. Calculate your peak and end debt

    We model your highest temporary debt, expected loan after sale, likely interest and required repayments.

  3. Compare your bridging options and risks

    We explain suitable lenders, maximum terms, sale conditions and what happens if your current home takes longer to sell.

  4. Manage your approval and valuations

    We prepare your application and coordinate the lender assessment and valuation requirements for both properties.

  5. Coordinate your purchase and sale

    We work with the lender and your conveyancer or solicitor to help manage your settlement and repayment of the bridging debt.

Bridging loan FAQs

It is temporary finance that covers the period when you own the new and existing properties at the same time. Sale proceeds from the existing home are then used to reduce the debt.