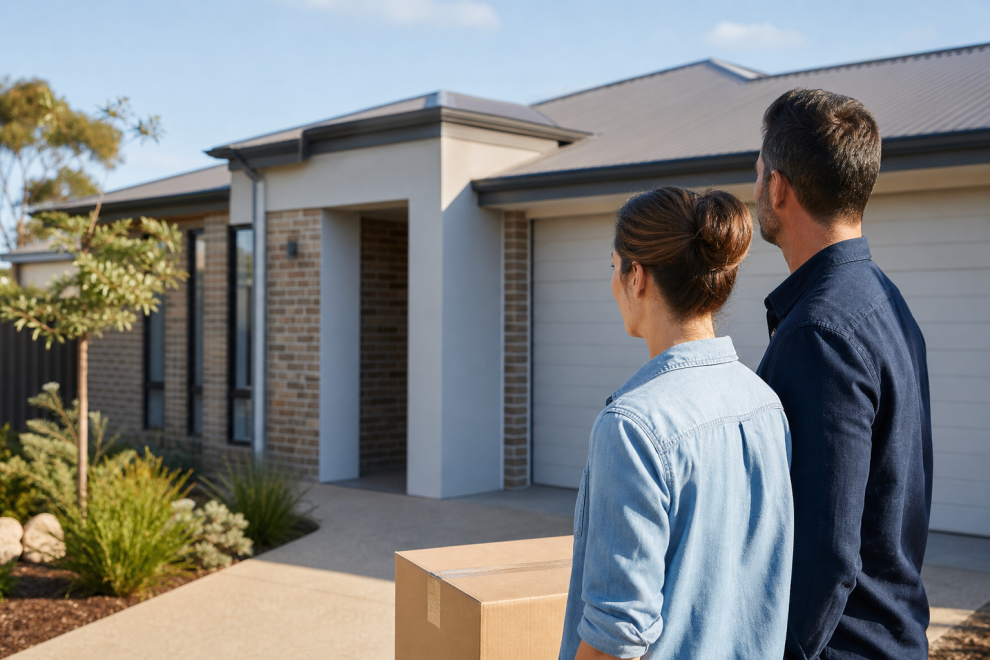
Move into your next home with a clear finance plan
We help homeowners understand their equity, likely borrowing power and options for buying and selling in the right order.
- Estimate available equity and purchase costs
- Compare selling first, buying first and bridging options
- Plan deposits and overlapping repayments
- Coordinate finance and settlement milestones
40+Lenders
EquityReview
MoveTiming
Home loan help when you are moving house
Buying your next home can involve two properties, two contracts and two settlement dates. Before making an offer, understand how much usable equity you may have, what happens if your current home sells for less than expected and whether you could carry both loans for a period.
AAA Mortgage Solutions can model different scenarios and compare home loan structures suited to your planned move.
Buying before selling may involve bridging finance, while keeping your current home may require a review of suitable investment loan options. A refinance review can also help clarify available equity and whether the existing loan structure still suits your plans.
How a mortgage broker helps you buy your next home
-
Understand your equity and budget
We review your current loan, estimated property value, usable equity and the likely costs of your next move.
-
Plan your buying and selling sequence
We explain the options for selling first, buying first or using bridging finance and help you plan the timing.
-
Compare your loan options
We compare loan structures for your current and next property, including repayments, features and overall costs.
-
Arrange your finance approval
We prepare and manage your application, valuations and lender requirements for your proposed purchase.
-
Coordinate your settlement
We work with the lender and your conveyancer or solicitor to help keep your sale, purchase and finance dates aligned.
What home loan clients have to say
Real stories from people we helped make clearer, more confident loan decisions.
FAQs about buying your next home
Yes, if you can fund the deposit and meet the lender's requirements for the peak debt. Options may include savings, equity release or bridging finance.
Allow for selling-agent and marketing fees, conveyancing, discharge and new-loan costs, inspections, government charges, removalists, insurance and possible temporary accommodation or overlapping interest.
Bridging finance temporarily covers the gap between purchasing the new home and selling the existing one. The lender assesses the highest combined debt and the expected debt remaining after sale.
Potentially. Equity is the property's value less the debt secured against it, but lenders generally allow access only up to their acceptable loan-to-value ratio and subject to serviceability.
Sell first for greater price and funding certainty; buy first for greater control over finding the next home. The better choice depends on cash reserves, serviceability, market conditions and your tolerance for timing risk.
Yes, some loan structures use both the current and new properties as security. Understand how this affects flexibility, sale proceeds and the process for releasing the old property after settlement.
Options may include negotiating a simultaneous or extended settlement, using short-term bridging finance or arranging temporary accommodation. These arrangements should be planned before contracts become unconditional.