08 8182 5555

Alternative income evidence, not an evidence-free loan

Low-doc lending may help eligible self-employed borrowers who cannot yet provide standard tax returns. We compare acceptable evidence and total cost.

  • BAS and business account statement options
  • Accountant declarations where accepted
  • Residential and eligible business purposes
  • Clear plan for documentation and future review
08 8182 5555
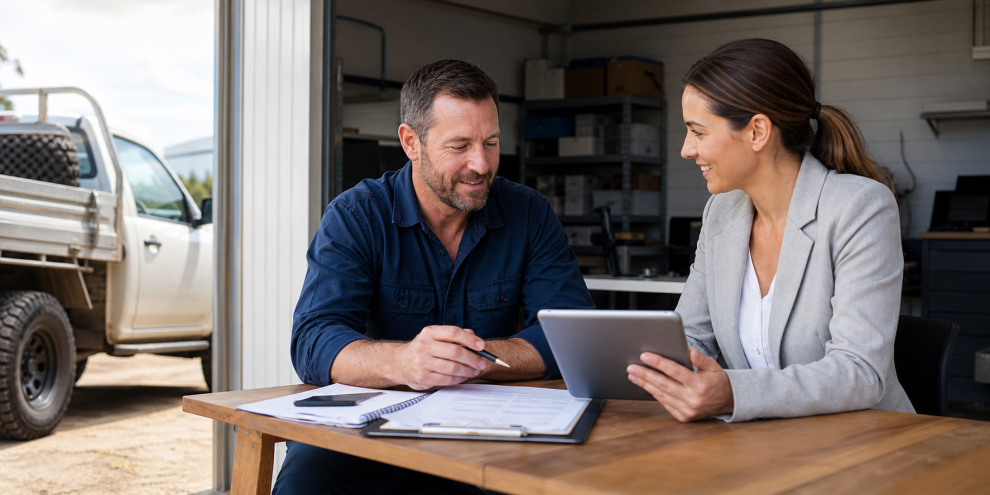
Australian business owner reviewing low doc lending options with a broker
Alt DocOptions
IncomeEvidence
40+Lenders
South Australian Owned Independent and local
Established in 1999 Decades of experience
Licensed credit provider Australian Credit License 385791
Bank + non-bank options Approved lender panel
Low doc loan paperwork discussion for an Australian small business owner

What is a low-doc loan?

A low-doc loan uses lender-approved alternative evidence to assess income. The borrower still needs to disclose their financial position and satisfy the lender that the loan is suitable and affordable.

Rates, fees, maximum loan-to-value ratios and property rules can differ from standard full-document loans.

Low doc lending is generally considered in the context of self employed home loans when current evidence does not fit a standard assessment. It may apply when purchasing or refinancing a home loan, depending on the lender and available documents. If credit, property or policy issues also affect the application, specialist and non conforming loans may need to be considered.

How a mortgage broker helps with a low doc loan

  1. Understand your document gap

    We clarify why your standard financial documents are unavailable and what current evidence you can provide.

  2. Gather your strongest evidence

    We review your BAS, business account statements, accountant declarations and other documents accepted by relevant lenders.

  3. Compare lender policy and cost

    We compare verification requirements, deposit or equity rules, rates, fees and risk based pricing for your situation.

  4. Prepare and manage your application

    We present your income evidence clearly, lodge your application and respond to lender questions.

  5. Plan for your future review

    We explain when a full document refinance may become realistic and remain available to review your loan.

Low doc loan FAQs

It is generally intended for eligible self-employed borrowers with established income but without the standard up-to-date tax documents a lender would normally request.