Construction finance, one stage at a time
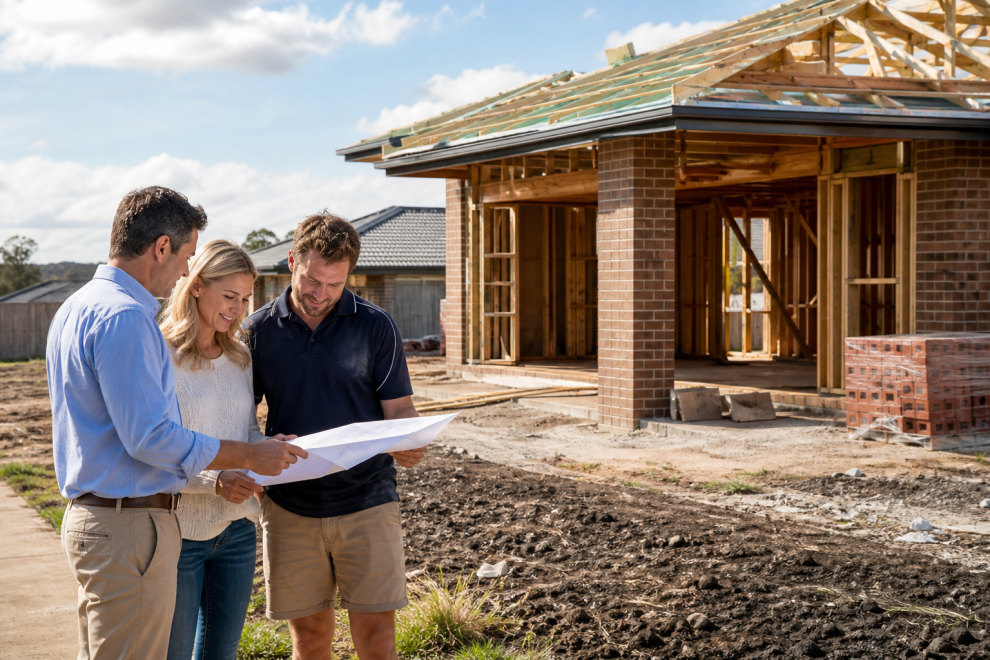
Building a home involves more than one settlement. We help you prepare the contract, budget and loan for staged progress payments.
- Finance land, construction or both
- Understand progress payments and valuations
- Check the documents your lender may require
- Plan for variations, upgrades and cost overruns
BuildBudget
ProgressPayments
40+Lenders
Construction loans for building in South Australia
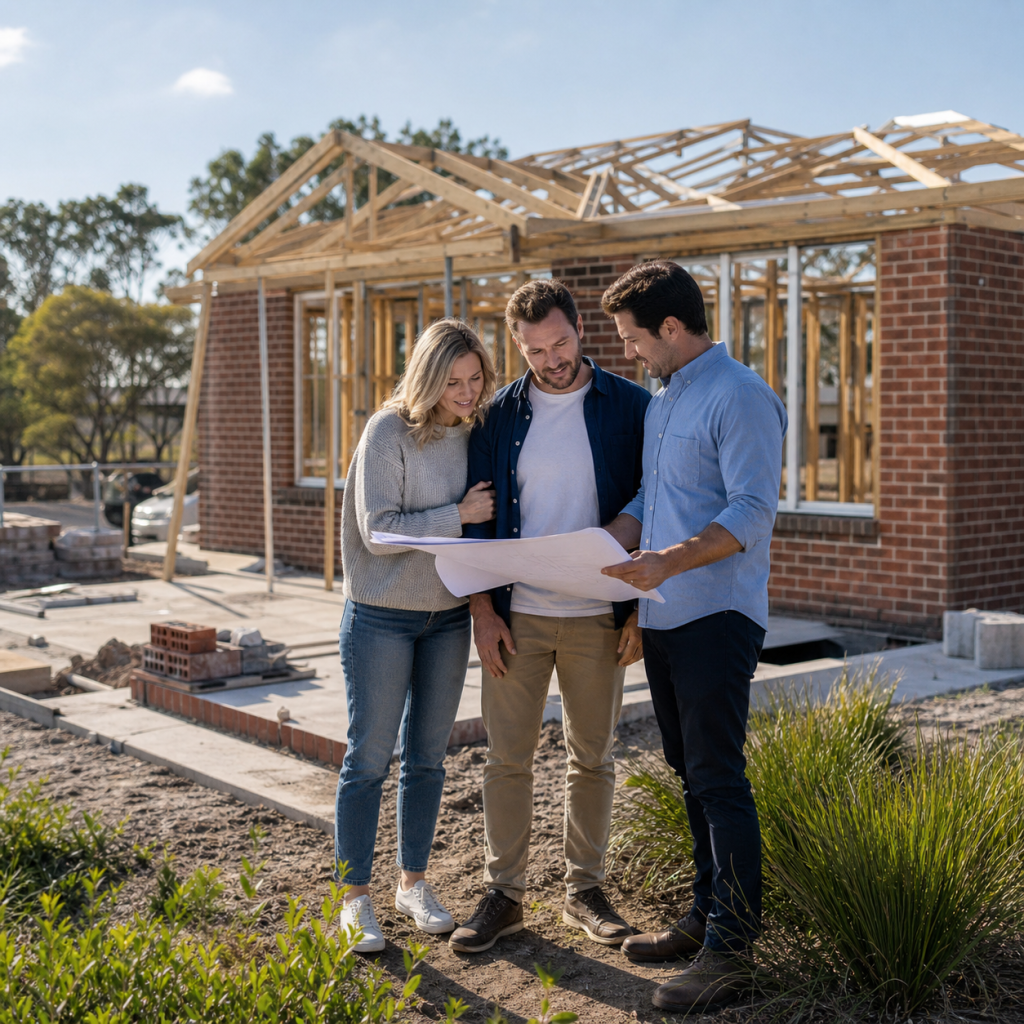
A construction loan is generally drawn in stages as the builder completes agreed work. Interest is usually charged on the amount drawn rather than the full approved construction limit, subject to the lender’s terms.
The lender will normally assess you, the property, plans, specifications, approvals and building contract before construction begins.
If this will be your first home, start with the first home buyer information covering deposits, costs and available assistance. Buyers with a smaller deposit may also need to compare low deposit home loans. If the completed property will be rented, review investment loan structures before choosing the repayment setup.
How a mortgage broker helps with a construction loan
-
Plan your complete budget
We help you account for your land, building contract, site costs, variations, professional fees and a sensible buffer.
-
Check your project documents
We review your plans, specifications, approvals, insurance and building contract against lender requirements.
-
Compare your construction loan options
We compare suitable lenders, rates, fees, valuation policies and progress payment processes.
-
Manage your approval and progress payments
We lodge your application and help coordinate the lender requirements, invoices and evidence needed at each stage.
-
Complete your loan process
We help manage your final lender requirements before your loan moves to its ongoing repayment structure.
What construction loan clients have to say
Real stories from people we helped make clearer, more confident loan decisions.
Construction loan FAQs
Land usually settles in one payment, while construction funds are released in stages. The lender assesses the combined project, your contribution and the expected value when the home is complete.
The lender reviews your financial position and project documents, orders a valuation based on the plans and contract, confirms conditions and issues loan documents before building funds can be drawn.
Progress payments are staged payments to the builder after agreed milestones, such as slab, frame, lock-up, fixing and completion. The lender may require invoices, inspections or other evidence before releasing funds.
Include land, site works, demolition if relevant, design and engineering, approvals, connections, landscaping, floor coverings, window treatments, variations, interest during construction and contingency funds.
You can discuss borrowing capacity earlier, but formal construction approval normally requires the plans, specifications and relevant approvals or evidence acceptable to the lender.
Common requirements include a signed building contract, plans, specifications, progress-payment schedule, builder licence and insurance details. Requirements vary by project and lender.
Yes. A fixed-price contract is commonly required, but check exclusions, provisional sums, prime-cost items and variation clauses because the final amount can still change.
You may need to use your own funds, revise the project or apply for additional lending. Extra finance is not guaranteed, so keep a contingency and approve variations carefully.
Potentially. Once completion requirements are met, you can review the ongoing loan and compare other options. Consider valuation, discharge costs and whether any fixed-rate or lender conditions apply.